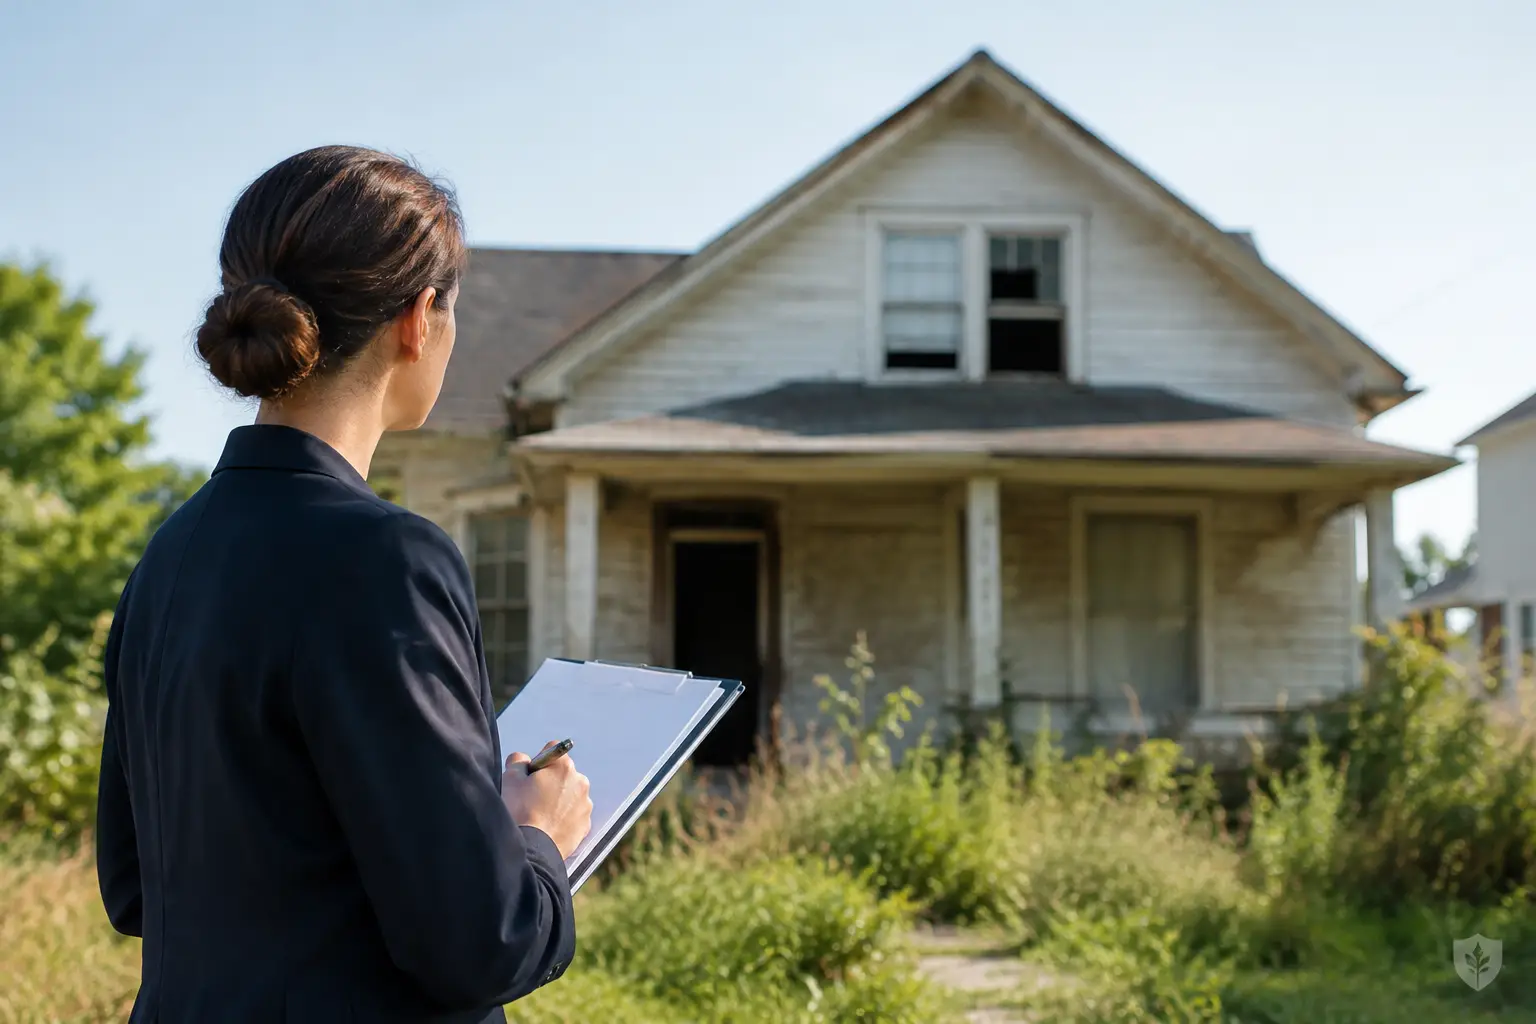
An empty house can lose value long before it appears on a surveyor’s report. Vacant property risks build quietly: a small leak becomes saturated ceilings, an unsecured rear window invites theft, and an insurance policy may restrict cover after a defined period of unoccupancy. For owners needing a sale and investors considering a refurbishment project, vacant stock needs active control, not occasional attention.
The key distinction is between a property that is merely empty and one that is unmanaged. A short void between tenancies may be routine. A probate property left unattended for several months, or a house awaiting finance, planning or renovation, presents a different risk profile altogether. The longer it remains empty, the more its condition, security and carrying costs can move against the owner.
Why vacant property risks escalate quickly
Occupied homes benefit from passive monitoring. Residents notice a failed boiler, a dripping overflow, a loose roof tile or a broken lock. They heat and ventilate the building, collect post, move bins and create the regular signs of occupation that discourage opportunistic crime.
Once a property is vacant, those controls disappear. Defects that would normally be resolved within hours can continue for weeks. Water damage is the most common example. A failed flexi hose, burst pipe or defective roof covering can cause extensive damage to plaster, joinery, electrical installations and neighbouring properties before anyone enters the building.
Security is equally practical. Vacant homes are more likely to attract trespass, metal theft, fly-tipping, forced entry and vandalism. Damage is not always dramatic. Missing copper pipework, a compromised lock, stripped kitchen units or a smashed ground-floor window can delay a refurbishment and create wider insurance and compliance issues.
There is also an economic cost. Council tax, mortgage payments, utilities, insurance premiums and basic maintenance continue while the asset produces no income. In a slow transaction or poorly planned refurbishment, those holding costs can materially erode projected profit.
Insurance is a condition, not a formality
Many owners assume their standard buildings policy remains unchanged while a house is empty. That assumption can be expensive. Policies often define an unoccupied period, commonly 30 or 60 consecutive days, after which cover may reduce or additional conditions apply. Escape of water, theft and malicious damage are frequent areas of restriction.
The exact position depends on the policy wording. Some insurers require written notification, minimum heating levels, regular inspections, a working alarm, secure locks or water isolation. Others may require specialist unoccupied property cover. Failing to meet an inspection condition can create a dispute when a claim is made, even where the underlying damage is genuine.
Owners should confirm the position before the property becomes vacant, not after an incident. Record the insurer’s requirements, nominate a responsible person and retain a simple inspection log with dates, photographs and actions taken. This is not paperwork for its own sake. It creates evidence that the property has been actively managed.
For an investor acquiring an empty property, insurance should be reviewed before exchange where possible and certainly from completion. Existing cover does not automatically transfer, and renovation works can change the risk again. A standard residential policy may not be suitable once the building is stripped out, services are altered or contractors are regularly on site.
The hidden building risks in an empty home
Vacancy tends to expose defects that were already present. A marginal roof issue can become a major water ingress event during a period of heavy rain. Blocked gutters can overflow into eaves and wall cavities. Condensation and poor ventilation can encourage mould, particularly where heating has been switched off.
Services require the same discipline. Water left live in an empty building creates avoidable exposure, especially in colder weather. Depending on the property and insurance requirements, isolating and draining the water system may be appropriate. Gas and electrical installations should be assessed by competent professionals, particularly where the property has been neglected, altered by previous occupants or is due for refurbishment.
External condition matters too. Overgrown gardens advertise vacancy, conceal access points and can create boundary disputes. Loose fencing, unstable outbuildings and damaged paths increase liability if a visitor or neighbour is injured. In blocks of flats, an empty leasehold unit can still affect other residents through leaks, fire safety concerns and service-charge obligations.
A measured inspection should identify immediate defects, likely deterioration and the scope of works required to bring the property back into a safe, marketable condition. Estate-agent photographs and a quick viewing are not a substitute for construction-led assessment. The issue is not simply what can be seen on the day. It is what the building is likely to cost once access, strip-out and intrusive works reveal the underlying condition.
A controlled approach to vacant property management
The appropriate level of management depends on location, condition, length of vacancy and intended exit. A modern flat empty for two weeks before completion needs a different plan from a detached probate house awaiting six months of major works. However, the operational basics are consistent.
A practical control plan should cover five areas:
- Secure all points of entry, including side gates, loft hatches, garages and rear windows. Repair defective locks rather than relying on temporary measures.
- Check insurance conditions and arrange the correct cover for the period of vacancy and any planned works.
- Inspect at an agreed frequency, recording internal and external condition, meter readings, signs of water ingress and any security concerns.
- Manage services deliberately, including water isolation, heating settings, alarm monitoring and safe access for contractors.
- Maintain the exterior through post collection, refuse removal, basic grounds maintenance and prompt repair of visible defects.
The value of a schedule is control. It assigns responsibility and prevents assumptions between family members, agents, contractors and investors. If several parties have access, keep a clear key record and restrict entry to those who need it.
Vacant properties during sale or refurbishment
For a seller, the decision is often whether to spend money managing and improving an empty property before marketing it, or to sell it in its current condition. There is no universal answer. Light maintenance and security work can protect value and improve saleability. Major cosmetic expenditure is less certain, especially where a buyer is likely to undertake a full refurbishment anyway.
The right decision depends on the property’s condition, local demand, expected sale route and timescale. A house with an obvious roof leak or unsafe electrics needs risk addressed, whether it is sold conventionally or directly. By contrast, replacing a dated kitchen may add little where the asset is priced as a renovation opportunity.
For investors, vacant property risk belongs in the appraisal, not in a footnote. Holding periods should include realistic allowances for legal delays, planning decisions, finance conditions, contractor availability and contingency. Refurbishment budgets should account for damage or defects that may emerge after purchase. The cheapest acquisition can become the most expensive project when the condition survey is superficial and the programme is optimistic.
Sentinel Property Ventures approaches this through documented due diligence: measured assessment of the building, clear scope definition and a realistic view of cost, time and exit. That discipline is particularly valuable where a property has been vacant long enough for hidden defects to develop.
When vacancy becomes a decision point
A vacant property should trigger a review of the owner’s strategy. If the intention is to let, establish the works required, compliance pathway and likely rental demand before costs drift. If the intention is to sell, decide whether the property should be stabilised, refurbished or sold as a clear renovation proposition. If there is no defined route, the vacancy can become an expensive holding pattern.
The most effective response is not necessarily the most elaborate one. It is a proportionate plan that secures the building, meets insurance conditions and protects the asset while a sale, letting or development decision is made. Empty properties deteriorate when nobody is accountable for them. Give the building a plan, an inspection rhythm and a clear next step.